The Biggest Credit Hurdle for Renters Who Want To Buy in Metro Portland & SW Washington
The Biggest Credit Hurdle for Renters Who Want To Buy in Metro Portland & SW Washington
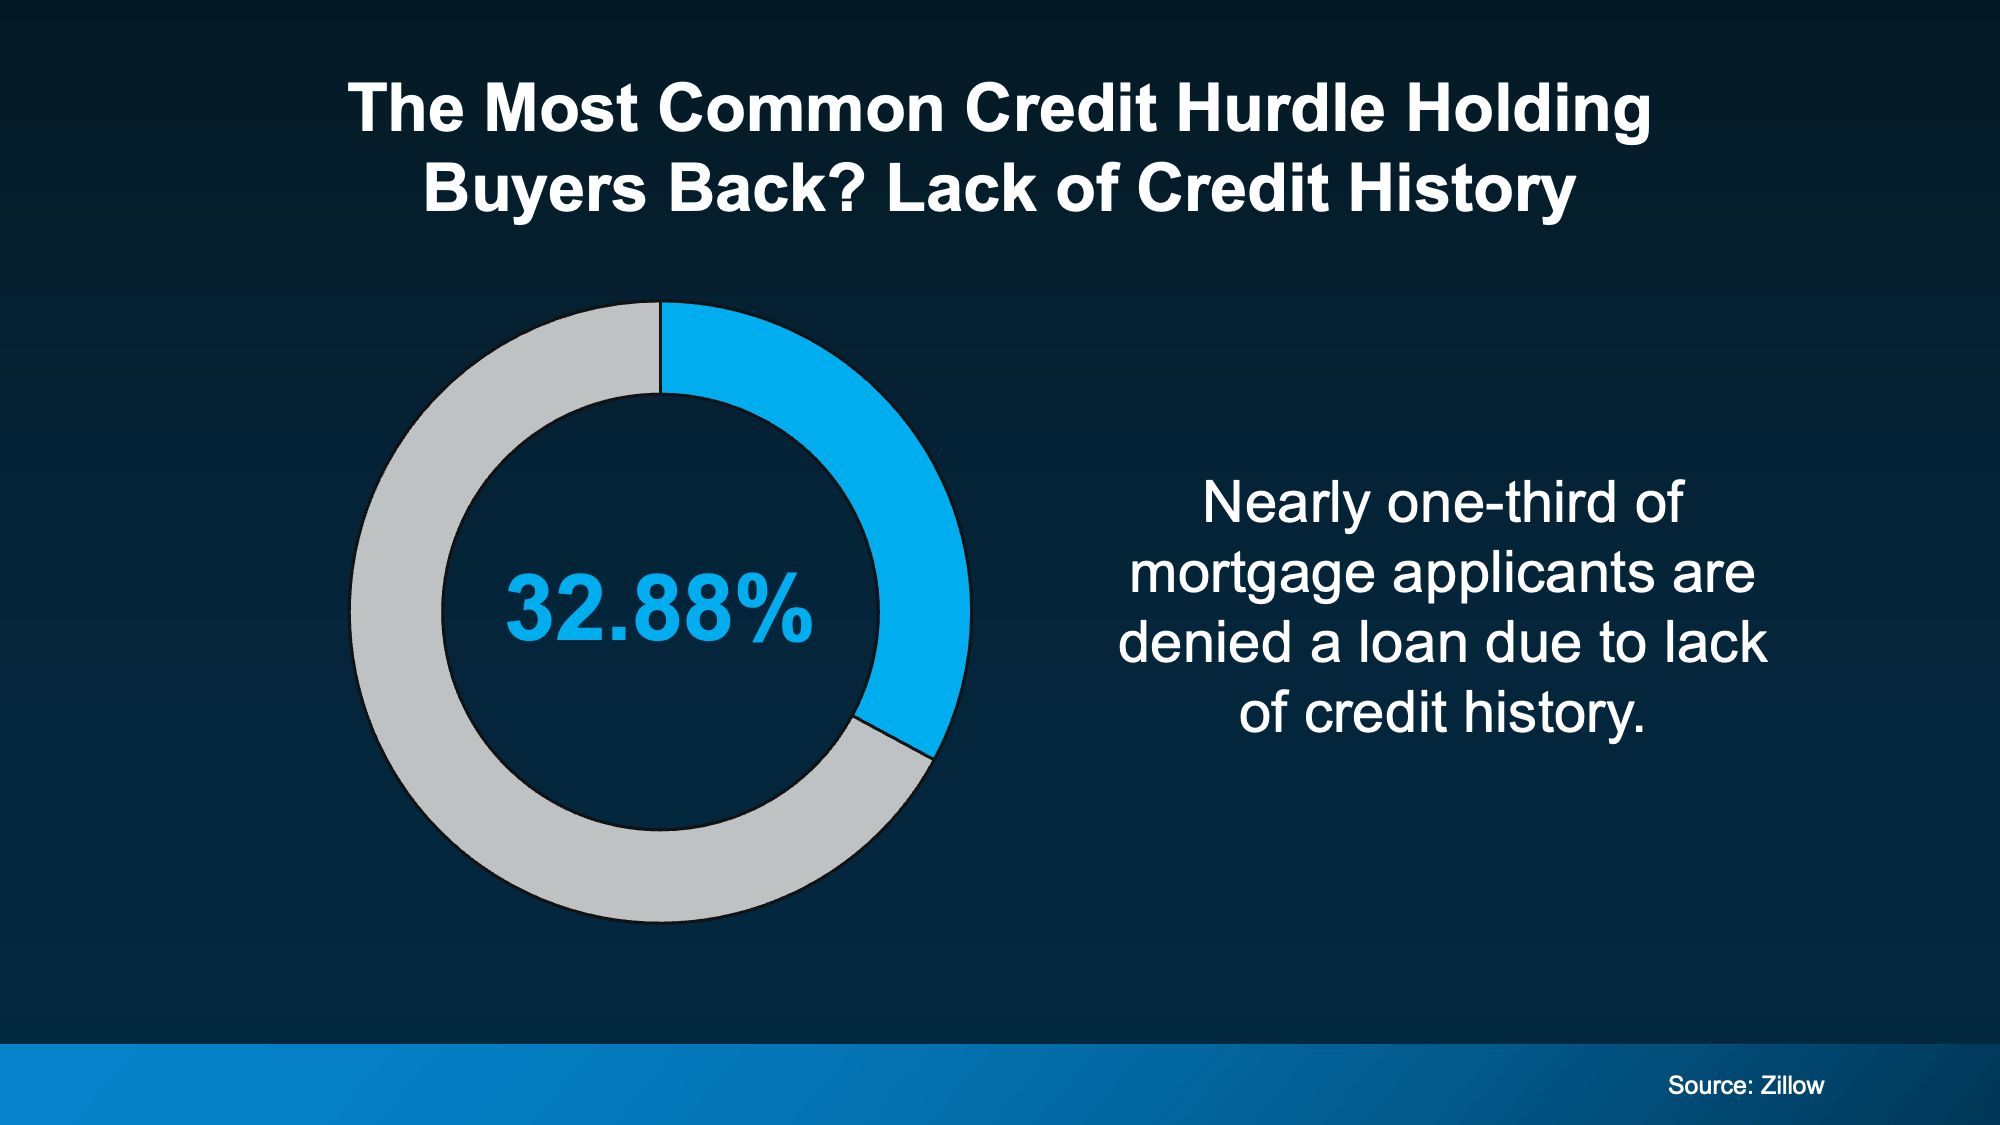
 Key Takeaway: As of late 2026, the primary barrier preventing aspiring first-time homebuyers across the Portland-Vancouver Metropolitan Area (covering Clark County in Washington, and Multnomah, Washington, and Clackamas Counties in Oregon) from qualifying for a mortgage is not past defaults or high credit card debt—it is simply a lack of established credit history. National research from Zillow reveals that nearly one-third of all rejected mortgage applicants (32.88%) are denied due to insufficient credit profiles. For years, local renters in Portland and Vancouver paying $1,800 to $2,600+ on time every month received zero credit recognition for their single largest monthly expense. However, Federal Housing Finance Agency (FHFA) approvals of modernized credit scoring models (including VantageScore 4.0 and updated FICO algorithms) now allow verified, on-time rental payment histories to be factored directly into underwriting. A VantageScore study indicates this change can unlock mortgage eligibility for nearly 4 million U.S. renters. Pairing proactive rent reporting with regional down payment assistance and local buyer negotiation strategies opens the door to homeownership across our Pacific Northwest communities.
A Note of Comfort for Your Journey (Entity Connection)
If you've spent years paying substantial rent on time every single month while feeling discouraged that lenders still view your credit profile as "insufficient," take a deep breath. Feeling frustrated when you know you manage your household cash flow responsibly is completely valid. Please take comfort in knowing that the mortgage credit landscape has fundamentally shifted in your favor across Oregon and Southwest Washington. You are no longer locked out simply because you haven't accumulated traditional car loans or high credit card balances. As experienced local real estate advisors and dedicated housing advocates, Ken and Susan Rosengren with Lucido Global at Keller Williams Premier Partners are here to help you turn your proven rental track record into purchasing power. Call Ken directly at 360.609.0226 or Susan at 360.607.6678. We wrap a clear, protective strategy around your financing and home search so you can step into homeownership with complete peace of mind.
 🗺️ The Modern Credit Shift: Why Rent Reporting Unlocks First-Time Buying
Understanding how credit scoring guidelines are evolving helps local renters convert their monthly housing payments into an approved mortgage file:
-
The "Thin File" Dilemma: Many renters deliberately avoid taking on high-interest credit card debt or unnecessary installment loans. Ironically, this financial discipline often leaves them with a "thin credit file," which automated underwriting systems historically flagged as unscoreable or high risk.
-
Modern Underwriting Models: Modernized scoring systems evaluate non-traditional credit data, including 12 to 24 months of verified on-time residential lease payments, water/electric utilities, and telecommunications bills. Fannie Mae and Freddie Mac automated underwriting systems now incorporate positive rental payment history directly into risk assessments.
-
Action Is Required: Landlords and property managers do not automatically report rental payments to the major credit bureaus (Experian, Equifax, TransUnion). Renters must proactively opt into reporting services or request that their management company utilize an automated reporting platform.
📊 Regional Market & Starter Home Snapshot: Metro Portland OR vs. Clark County WA (Late 2026 Data)
To understand the price points and inventory conditions awaiting newly qualified buyers across our bi-state metro area, review current RMLS and regional baseline metrics:
| Local Submarket Hub | Median Closed Home Price | Months' Supply of Inventory | Average Days on Market | Entry-Level Starter Price Band |
| Portland Metro Area (OR) | $545,000 | 4.3 Months | 67 Days | $280,000 - $420,000 (Condos, Townhomes, East Portland) |
| Clark County / Vancouver (WA) | $550,000 | 4.4 Months | 74 Days | $320,000 - $430,000 (Central Vancouver, Hazel Dell, Orchards) |
| Suburban Growth Corridors (Gresham, Battle Ground, Hillsboro) | $480,000 - $515,000 | 4.1 - 4.4 Months | 68 - 75 Days | $340,000 - $440,000 (Subdivisions & Builder Inventory) |
💡 Practical Playbook: 6 Proactive Steps to Build Your Buying Profile
Rent reporting is a powerful tool, but maximizing your borrowing qualification requires a coordinated effort:
1. Activate Verified Rent Reporting Immediately
Ask your landlord or property management company if they participate in rent-reporting platforms (such as RentTrack, Boom, Esusu, or Pinata). If your independent landlord does not offer automated reporting, you can enroll independently through consumer services that verify bank transactions and transmit payment history directly to Experian, TransUnion, and Equifax.
2. Clean Up Inaccuracies on Your Credit Reports
Request free copies of your credit reports through AnnualCreditReport.com. The Consumer Financial Protection Bureau (CFPB) notes that errors (such as outdated collections, incorrect balances, or misspelled names) are common. Disputing and removing erroneous reporting can lift your score by 20 to 40+ points within 30 to 60 days.
3. Maintain Core Credit Disciplines
-
Keep Revolving Utilization Low: Maintain credit card balances below 10% to 30% of your maximum credit limits.
-
Preserve Account Longevity: Do not close old, zero-balance credit cards; closing seasoned accounts shortens your average credit history and can drop your overall score.
-
Avoid New Hard Inquiries: Refrain from applying for auto loans, furniture financing, or new credit cards within 6 to 12 months of applying for a mortgage.
4. Layer Pacific Northwest Down Payment Assistance (DPA)
Once your credit score qualifies, pairing your approval with state programs minimizes out-of-pocket cash needs:
-
Washington Buyers (WSHFC): The Washington State Housing Finance Commission provides the Home Advantage Program, offering a 0% interest, deferred second loan covering 3% to 5% of your purchase price toward your down payment or closing costs.
-
Oregon Buyers (OHCS): Oregon Housing and Community Services offers FirstHome and Cash Advantage programs providing low-interest mortgages and down payment grants.
5. Leverage Current Market Inventory for Seller Concessions
With regional inventory expanding to 4.3 to 4.4 months of supply and homes averaging 67 to 74 days on market, buyers hold significant negotiating leverage. Rather than struggling with high interest rates, ask the seller for a $10,000 to $15,000 credit at closing to fund a 2-1 temporary rate buydown, dropping your effective interest rate by 2.0% in year one (e.g., from 7.18% down to 5.18%).
6. Utilize Custom Digital Valuation & Planning Tools
If you or a co-signer own an existing property or are planning an upcoming transition, take advantage of our specialized digital tools:
-
Calculate Current Property Equity: Request a customized equity analysis via our Free Home Valuation Landing Page.
-
Planning an Independent Sale? Access checklists, worksheets, and resources via our Free FSBO Success Program Landing Page.
🛠️ The Bottom Line: Your Rental History Is Your Stepping Stone
A thin credit history no longer has to stand between you and homeownership. By taking proactive steps to report your on-time rent, optimizing your debt ratios, and partnering with knowledgeable local advisors, you can transition from paying your landlord's mortgage to building equity in your own Pacific Northwest home.
Whether you are exploring starter condos in Portland, single-family homes in Vancouver, or townhomes in Beaverton and Gresham, our team is here to guide you through every milestone.
Reach out today, and let's connect you with trusted local lenders who specialize in modern credit programs!
Connect with Our Team Today
No high-pressure sales pitch. No automated scripts. Just honest local numbers, deep community insights, and a protective strategy built entirely around your family's financial goals.
Ken Rosengren
📞 Phone: 360.609.0226
📧 Email: KenRosengren@LucidoGlobal.com
Susan Rosengren
📞 Phone: 360.607.6678
📧 Email: SusanRosengren@LucidoGlobal.com
Lucido Global at Keller Williams Premier Partners
2211 E Mill Plain Blvd, Vancouver, WA 98661
Helping families build long-term wealth through education, planning, and homeownership.
#PortlandRealEstate #VancouverWARealEstate #ClarkCountyWA #LucidoGlobal #FirstTimeHomeBuyer #RentReporting #CreditScoreTips #MortgageApproval #PNWRealEstate #RealEstateExpert #MarketLeaderPNW #PremierAgent
Categories
- All Blogs (660)
- For Sale By Owner (21)
- Local Events (39)
- Portland Metro (2)
- 100 Hands for Foster Care (2)
- 1031 Exchange PNW (1)
- Affordability (70)
- Agent Value (105)
- Battle Ground (2)
- Boutique Neighborhoods (1)
- Brush Prairie WA (1)
- Buying Tips (237)
- Camas High Schools (1)
- Camas WA (1)
- Camas WA Home Buying (1)
- Camas WA Real Estate (2)
- Central Hub (1)
- Clark County Housing (25)
- Clark County WA Schools (3)
- Closing Costs (1)
- Community Support (17)
- Cowlitz County (1)
- Credit Tips (3)
- Debt-Free Living, (1)
- Design (8)
- Downsize (13)
- Downsizing Vancouver WA (13)
- Economy (28)
- Equity (37)
- Evergreen High Schools (1)
- Expired Listings (1)
- Featured (20)
- Felida WA Home Buying (1)
- Felida WA Real Estate (1)
- Financial Planning (43)
- First-Time Home Buyer (197)
- For Investors (1)
- For Sale by Owner (6)
- Forecasts (17)
- Foreclosures (6)
- Foster Care Resrources (2)
- Fun Tips (10)
- Giving Back (1)
- Historic Charm (1)
- Historical Character (1)
- Hockinson WA (1)
- Home Buying (299)
- Home Improvement (1)
- Home Inspections (3)
- Home Prep & Staging (5)
- Home Prices (77)
- Home Selling (206)
- Home Staging PNW (1)
- Home Value (10)
- Housing Market Confidence (48)
- Independent Living PNW (2)
- Inventory (41)
- Kalama WA (1)
- La Center (1)
- Landlord Tips (2)
- Lifestyle Move PNW (24)
- Listing Strategy (5)
- Local (107)
- Local Non-Profits (1)
- Longview WA (1)
- Luxury / Vacation (7)
- Market Update (66)
- Mid-Tier Housing (1)
- Mortgage (71)
- Move-Up (16)
- Moving for Job Relocation (5)
- Multi-Generational (1)
- Negotiation Strategy (4)
- New Construction (15)
- Newsletter (14)
- Open House (1)
- Portland Downsizing (10)
- Portland For Sale by Owner (1)
- Portland OR (9)
- Portland OR Affordability (42)
- Portland OR Home Buying (89)
- Portland OR Homes (9)
- Portland OR Real Estate (124)
- Portland OR Seller Tips (40)
- Portland Real Estate FAQs (10)
- Portland Recession Risk (1)
- Portland-Vancouver Home Value (13)
- Portland-Vancouver Inventory (10)
- Price It Right Portland (8)
- Real Estate Investing (8)
- Real Estate Tax Strategy (1)
- Rent vs Buy (19)
- Restaurant Reviews (5)
- Retirement Planning (2)
- Ridgefield WA (1)
- Ridgefield WA Home Buying (1)
- Rightsizing Vancouver WA (3)
- Seasonal (11)
- Selling Rental Property (2)
- selling tips (141)
- Senior Market (6)
- Silver Group (3)
- Suburban Living (3)
- Technology (1)
- Teens & Young Adults (11)
- Trends (15)
- Vancouver For Sale by Owner (2)
- Vancouver WA (9)
- Vancouver WA Affordability (37)
- Vancouver WA Home Buying (76)
- Vancouver WA Home Value (7)
- Vancouver WA Real Estate (126)
- Vancouver WA Selling Tips (40)
- Washougal WA (1)
- Wealth Building (20)
- Yacolt WA (1)
Recent Posts